Edited, memorised or added to reading queue
on 01-Mar-2020 (Sun)
Do you want BuboFlash to help you learning these things? Click here to log in or create user.
Flashcard 149636810
| status | not learned | measured difficulty | 37% [default] | last interval [days] | |||
|---|---|---|---|---|---|---|---|
| repetition number in this series | 0 | memorised on | scheduled repetition | ||||
| scheduled repetition interval | last repetition |
Parent (intermediate) annotation
Open itCurrency swaps are over-the-counter derivatives, and are closely related to interest rate swaps.
Original toplevel document
Currency swap - Wikipedia, the free encyclopediarrency swap, both principal and interest of loan is exchanged from one party to another party for mutual benefits.[2] Contents 1 Structure2 Uses 2.1 Hedging example 3 Examples4 Abuses5 History6 References7 External links Structure[edit] <span>Currency swaps are over-the-counter derivatives, and are closely related to interest rate swaps. However, unlike interest rate swaps, currency swaps can involve the exchange of the principal.[1] There are three different ways in which currency swaps can exchange loans: The simplest
Flashcard 1671278759180
 is the compounding frequency per year (1 for annual, 2 for semi-annual, 12 for monthly, 52 for weekly, etc.),
 is the yield to maturity for an asset, periodically compounded
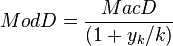
| status | not learned | measured difficulty | 37% [default] | last interval [days] | |||
|---|---|---|---|---|---|---|---|
| repetition number in this series | 0 | memorised on | scheduled repetition | ||||
| scheduled repetition interval | last repetition |
Parent (intermediate) annotation
Open itwell-known relationship between modified duration and Macaulay duration if yield is periodically compounded (not continually): where: is the compounding frequency per year (1 for annual, 2 for semi-annual, 12 for monthly, 52 for weekly, etc.), is the yield to maturity for
Original toplevel document
Bond duration - Wikipedia, the free encyclopediauously compounded. Then expression (2) becomes: To find modified duration, when we take the derivative of the value with respect to the periodically compounded yield we find [5] Rearranging (dividing both sides by -V) gives: which is the <span>well-known relationship between modified duration and Macaulay duration: where: indexes the cash flows, is the compounding frequency per year (1 for annual, 2 for semi-annual, 12 for monthly, 52 for weekly, etc.), is the cash flow of the th payment from an asset, is the time in years until the th payment will be received (e.g. a two-year semi-annual would be represented by a index of 0.5, 1.0, 1.5, and 2.0), is the yield to maturity for an asset, periodically compounded is the present value of all cash payments from the asset. This gives the well-known relation between Macaulay duration and modified duration quoted above. It should be remembered that, even though Macaulay duration and modified duration are clo